

Option Alpha vs MesoSim
Option Alpha and MesoSim are both built for options traders who want to test systematic strategies before putting capital at risk, but they approach the workflow differently. Option Alpha combines options research, historical backtesting, portfolio analysis, paper trading, and no-code automation in one platform. MesoSim is a more research-focused, low-code options simulation environment designed for traders who want deeper control over multi-leg strategy logic, adjustments, execution assumptions, margin, Greeks, and portfolio-level analysis.
MesoSim currently supports five-minute historical options data for SPX back to May 2010 and RUT, VIX, and GLD back to January 2012. It also includes configurable mid-price or bid/ask fills, per-leg slippage, commissions, Reg-T and portfolio-margin-like models, 2D/3D risk graphs, volatility-surface analysis, StatSim resampling, portfolio construction, AI-assisted strategy development, and API access on higher-tier plans.
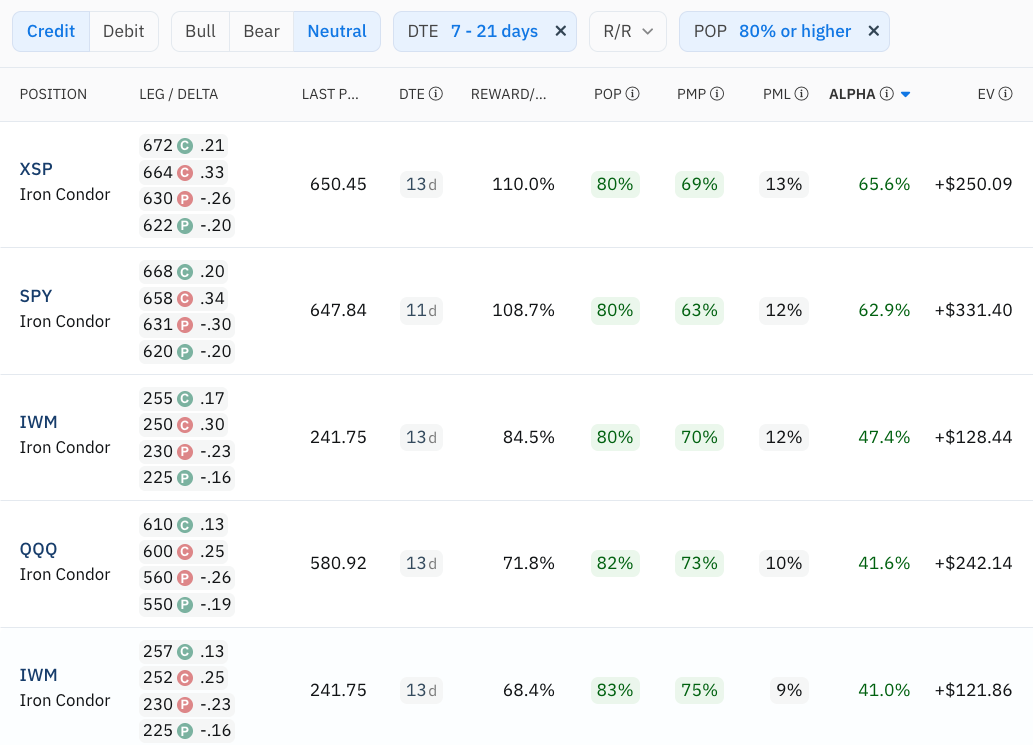
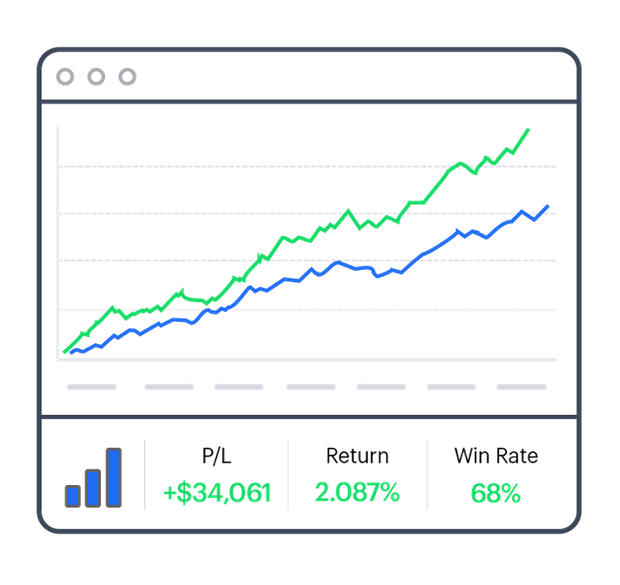
Option Alpha takes a more streamlined approach for traders who want to build and automate supported options strategies without coding. Its backtester supports 0DTE through 45 DTE, historical options data back to 2013 for supported symbols, one-minute backtesting data, side-by-side backtest comparisons, combined portfolio analysis, Strategy Insights, and direct bot generation from a tested strategy.
Choose Option Alpha if: you want a simpler no-code workflow for researching, backtesting, paper trading, and automatically executing supported options strategies through integrated brokerage accounts, especially if you want to move directly from a backtest into a fully automated bot without maintaining code or a local broker agent.
Choose MesoSim if: you prioritize deeper quantitative options research, highly customizable multi-leg strategy logic and adjustments, longer SPX history, configurable execution and margin modeling, advanced risk graphs, volatility-surface analysis, portfolio delta hedging, statistical resampling, API access, and AI-assisted low-code strategy development.
Option Alpha emphasizes accessibility and native automation; MesoSim emphasizes flexibility and research depth. Neither approach is inherently better. A trader who wants a visual, managed automation workflow may prefer Option Alpha, while a trader who wants more granular control over how an options strategy is modeled and analyzed may prefer MesoSim.




'%3e%3cg id='Final-Copy-2_2_' transform='translate(1275.000000, 200.000000)'%3e%3cpath class='st0' d='M7.4,12.8h6.8l3.1-11.6H7.4C4.2,1.2,1.6,3.8,1.6,7S4.2,12.8,7.4,12.8z'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3cg id='final---dec.11-2020'%3e%3cg id='_x30_208-our-toggle' transform='translate(-1275.000000, -200.000000)'%3e%3cg id='Final-Copy-2' transform='translate(1275.000000, 200.000000)'%3e%3cpath class='st1' d='M22.6,0H7.4c-3.9,0-7,3.1-7,7s3.1,7,7,7h15.2c3.9,0,7-3.1,7-7S26.4,0,22.6,0z M1.6,7c0-3.2,2.6-5.8,5.8-5.8 h9.9l-3.1,11.6H7.4C4.2,12.8,1.6,10.2,1.6,7z'/%3e%3cpath id='x' class='st2' d='M24.6,4c0.2,0.2,0.2,0.6,0,0.8l0,0L22.5,7l2.2,2.2c0.2,0.2,0.2,0.6,0,0.8c-0.2,0.2-0.6,0.2-0.8,0 l0,0l-2.2-2.2L19.5,10c-0.2,0.2-0.6,0.2-0.8,0c-0.2-0.2-0.2-0.6,0-0.8l0,0L20.8,7l-2.2-2.2c-0.2-0.2-0.2-0.6,0-0.8 c0.2-0.2,0.6-0.2,0.8,0l0,0l2.2,2.2L23.8,4C24,3.8,24.4,3.8,24.6,4z'/%3e%3cpath id='y' class='st3' d='M12.7,4.1c0.2,0.2,0.3,0.6,0.1,0.8l0,0L8.6,9.8C8.5,9.9,8.4,10,8.3,10c-0.2,0.1-0.5,0.1-0.7-0.1l0,0 L5.4,7.7c-0.2-0.2-0.2-0.6,0-0.8c0.2-0.2,0.6-0.2,0.8,0l0,0L8,8.6l3.8-4.5C12,3.9,12.4,3.9,12.7,4.1z'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3c/g%3e%3c/svg%3e) Your Privacy Choices