

Option Alpha vs QuantConnect
Option Alpha and QuantConnect both allow traders to backtest systematic strategies and deploy them through automated trading, but the platforms are designed for very different workflows. Option Alpha is purpose-built for options traders who want a visual, no-code environment for researching, backtesting, paper trading, and automating supported options strategies. QuantConnect is a code-first quantitative research and algorithmic trading platform built on the open-source LEAN engine, with strategies written primarily in Python or C#.
QuantConnect provides considerably more programming flexibility and broader market coverage. Its LEAN engine supports equities, options, futures, future options, forex, crypto, and other asset classes, along with custom portfolio construction, execution, risk models, parameter optimization, alternative datasets, local development, and a large collection of broker integrations. Its documented US equity options dataset includes minute-level historical data across thousands of symbols beginning in January 2012.
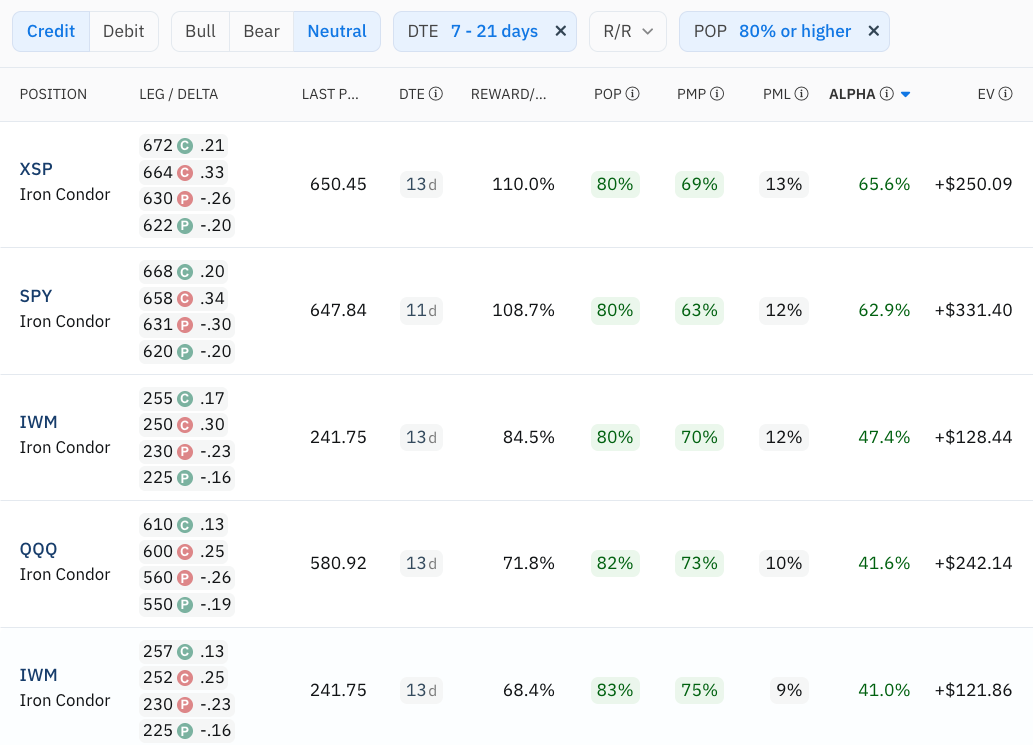
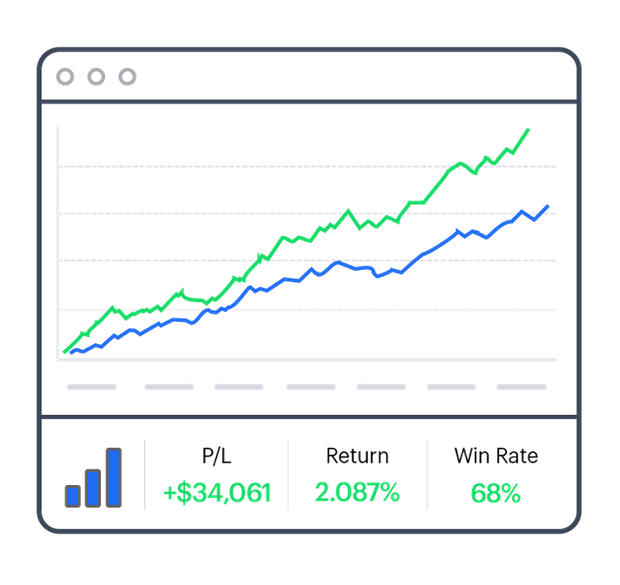
Option Alpha takes a more specialized approach. Traders can configure supported options structures, backtest strategies without writing code, compare strategy variations, combine backtests into portfolios, use Trade Ideas and Strategy Insights, optimize tests with AI, paper trade bots, and move supported backtests directly into automated execution. The primary decision between the platforms is therefore less about which has more raw capability and more about whether a trader wants maximum programmability and multi-asset flexibility or a streamlined no-code options workflow.
Option Alpha emphasizes accessibility and an integrated no-code options workflow, while QuantConnect emphasizes programmability, flexibility, multi-asset quantitative research, and institutional-grade algorithmic infrastructure.
Choose Option Alpha if: you primarily trade options and want a visual, no-code workflow for finding opportunities, configuring strategies, backtesting 0DTE through 45 DTE, comparing strategies, building portfolios, paper trading, and deploying fully automated bots without writing Python or C#.
Choose QuantConnect if: you want maximum programmability, broader asset-class support, thousands of option underlyings, custom portfolio and execution models, parameter optimization, alternative datasets, local development, open-source infrastructure, institutional tooling, or a much broader range of broker and exchange integrations—and are comfortable developing strategies in Python or C#.
Both platforms can: historically backtest options, automate live brokerage execution, model multi-leg strategies, paper trade, run algorithms in the cloud, optimize systematic strategies, and connect to Charles Schwab, tastytrade, Tradier, and TradeStation.




'%3e%3cg id='Final-Copy-2_2_' transform='translate(1275.000000, 200.000000)'%3e%3cpath class='st0' d='M7.4,12.8h6.8l3.1-11.6H7.4C4.2,1.2,1.6,3.8,1.6,7S4.2,12.8,7.4,12.8z'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3cg id='final---dec.11-2020'%3e%3cg id='_x30_208-our-toggle' transform='translate(-1275.000000, -200.000000)'%3e%3cg id='Final-Copy-2' transform='translate(1275.000000, 200.000000)'%3e%3cpath class='st1' d='M22.6,0H7.4c-3.9,0-7,3.1-7,7s3.1,7,7,7h15.2c3.9,0,7-3.1,7-7S26.4,0,22.6,0z M1.6,7c0-3.2,2.6-5.8,5.8-5.8 h9.9l-3.1,11.6H7.4C4.2,12.8,1.6,10.2,1.6,7z'/%3e%3cpath id='x' class='st2' d='M24.6,4c0.2,0.2,0.2,0.6,0,0.8l0,0L22.5,7l2.2,2.2c0.2,0.2,0.2,0.6,0,0.8c-0.2,0.2-0.6,0.2-0.8,0 l0,0l-2.2-2.2L19.5,10c-0.2,0.2-0.6,0.2-0.8,0c-0.2-0.2-0.2-0.6,0-0.8l0,0L20.8,7l-2.2-2.2c-0.2-0.2-0.2-0.6,0-0.8 c0.2-0.2,0.6-0.2,0.8,0l0,0l2.2,2.2L23.8,4C24,3.8,24.4,3.8,24.6,4z'/%3e%3cpath id='y' class='st3' d='M12.7,4.1c0.2,0.2,0.3,0.6,0.1,0.8l0,0L8.6,9.8C8.5,9.9,8.4,10,8.3,10c-0.2,0.1-0.5,0.1-0.7-0.1l0,0 L5.4,7.7c-0.2-0.2-0.2-0.6,0-0.8c0.2-0.2,0.6-0.2,0.8,0l0,0L8,8.6l3.8-4.5C12,3.9,12.4,3.9,12.7,4.1z'/%3e%3c/g%3e%3c/g%3e%3c/g%3e%3c/g%3e%3c/svg%3e) Your Privacy Choices